RBI Rate Hike Looms: What it Means for Your Home Loan & FD!
RBI Rate Hike Looms: What it Means for Your Home Loan & FD!
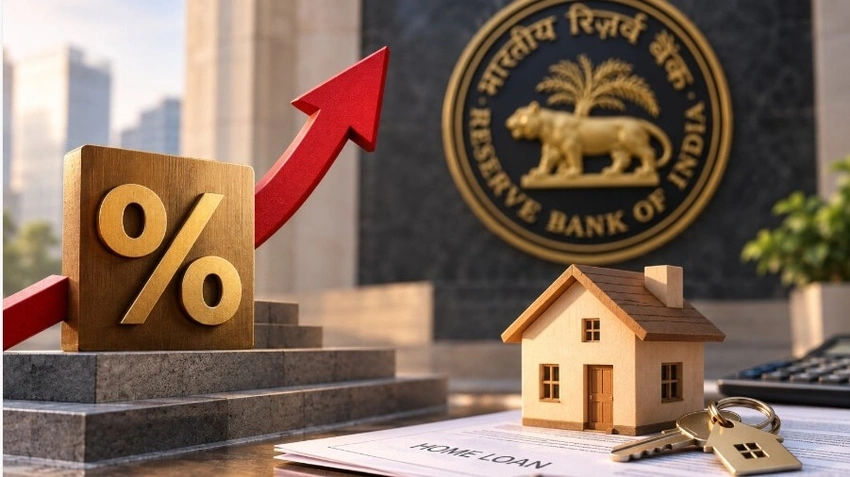
Brace yourselves! The RBI is likely to hike repo rates by 25 bps soon. Find out how this crucial decision could impact your home loan EMIs and fixed deposit returns. #RBIRateHike #HomeLoan
The Reserve Bank of India (RBI) is expected to announce its latest monetary policy decision on October 7, and economists are widely predicting a 25 basis point (0.25%) increase in the repo rate. This move, if it happens, would take the current repo rate from 5.25% to 5.50%, potentially ushering in a new cycle of rate hikes.
For millions of Indian homeowners with floating-rate loans, this spells higher monthly installments. While a 25 bps hike might seem small, its cumulative effect over a long tenure can be significant. For instance, a homeowner with a ₹50 lakh loan over 25 years could see their monthly EMI jump by approximately ₹817.
Over the entire loan period, this seemingly minor hike could add an extra ₹2.45 lakh to the total interest paid.
On the brighter side, savers have reason to cheer.
An increase in the repo rate typically translates to more attractive returns on fixed deposits (FDs). This could offer a welcome boost for individuals looking to park their savings and earn a better yield.
The RBI's potential decision is driven by a confluence of factors, including persistent higher inflation, rising global crude oil prices, a weakening rupee against major currencies, and the changing interest rate landscape worldwide. These economic pressures are strengthening expectations that the Monetary Policy Committee (MPC) will opt for a rate hike to help stabilize the economy.
As the October 7 policy decision draws near, both borrowers and savers are keenly watching the central bank's moves.
Understanding the implications of these changes is crucial for managing personal finances effectively in the evolving economic environment.
