CMPDIL IPO: Can it deliver long-term gains for risk-tolerant investors?
CMPDIL IPO: Can it deliver long-term gains for risk-tolerant investors?
CMPDIL plans to raise ₹1,842 crore via an offer for sale, riding steady coal demand and mineral exploration, but government dependence and green energy shifts pose risks.
Central Mine Planning & Design Institute (CMPDIL), a Miniratna PSU under Coal India, is set to raise ₹1,842 crore through an offer for sale. The promoter stake will fall from 100% to 85% after the IPO, signaling partial dilution while keeping government oversight.
The issue is valued at a trailing price-earnings multiple of 18, with a post-IPO P/E of about 21.6 for FY26, compared with 16.5 for Engineers India and 26.4 for RITES. The offer is aimed at long-term retail investors with a higher risk tolerance, given the company’s growth trajectory and exposure to policy shifts in the energy mix.
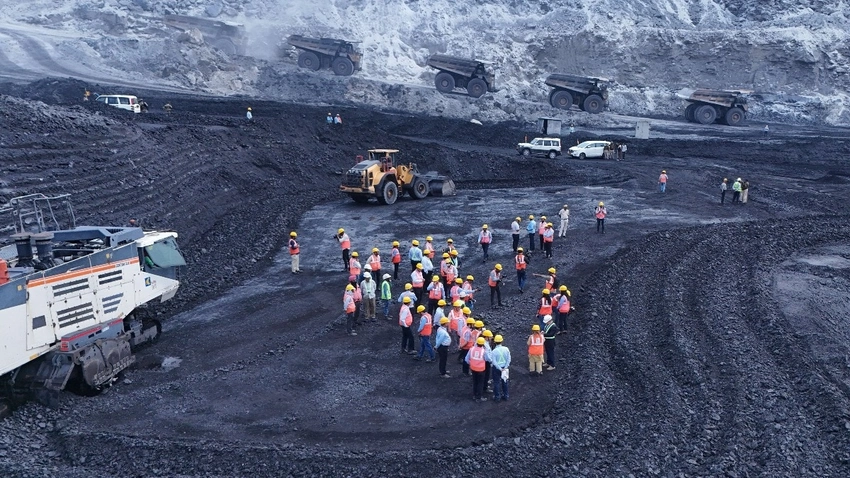
CMPDIL, incorporated in 1975, is a wholly owned subsidiary of Coal India and provides services across geological exploration, resource evaluation, mine planning and design, environmental engineering, geomatics, specialised technical studies, and management systems. In FY25, geological exploration and resource evaluation accounted for 46.2% of revenue, followed by mine planning and design at 21.2%, environmental management at 17.1%, and geomatics and survey services at 15.5%.
In FY25, CMPDIL held about a 61% market share, with Coal India being its biggest client contributing 66% of revenue. The company plans to diversify into consultancy for non-coal minerals such as lithium, copper, nickel, cobalt, bauxite and iron ore, and is exploring opportunities across Africa, South America and Australia while strengthening capabilities in related verticals. This diversification aligns with long-term growth visibility, even as two-thirds of revenue still comes from government entities, presenting concentration risk.
A key risk is potential policy shifts in favor of green energy, which could impact demand for CMPDIL’s core coal-focused services. Investors are advised to weigh these policy risks against the company’s expansion plans and international prospects. Additionally, the IPO does not involve fresh capital; it is primarily an offer for sale of promoter shares, with the price band set at Rs 163-172 per share for a minimum application of 80 shares and multiples thereof, with subscription windows in late March.
Overall, CMPDIL’s IPO presents a nuanced picture: a historically strong, government-linked revenue base, a clear push toward diversification, and exposure to evolving energy policies. It is best suited for investors comfortable with sector concentration risk and long-term horizons.
