HCLTech Q4 profit up 4.2%, AI revenue tops $620M
HCLTech Q4 profit up 4.2%, AI revenue tops $620M
HCLTech posts a solid Q4 with higher revenue and AI-led growth, while maintaining cautious FY27 guidance amid softer discretionary spend.
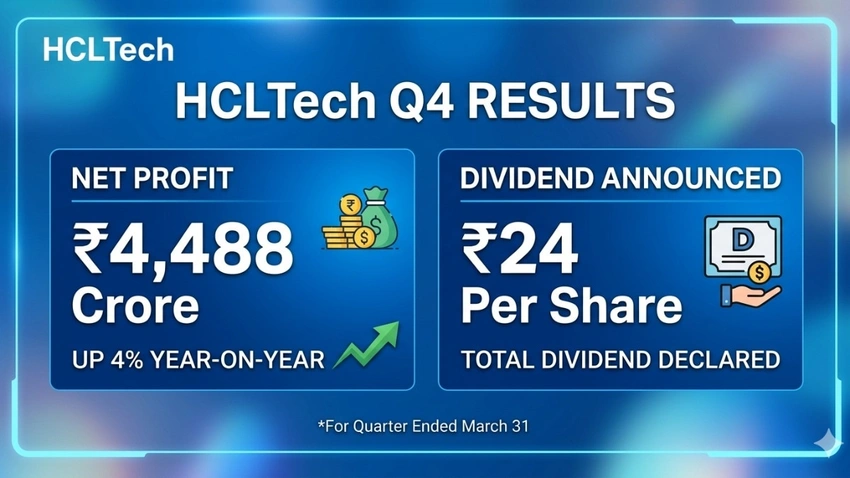
HCL Technologies posted a solid Q4, delivering a 4.2% year-on-year rise in consolidated net profit to Rs4,488 crore for the January-March quarter, alongside a 12.3% increase in revenue to Rs33,981 crore. In dollar terms, revenue stood at $3.68 billion, up 5.3% YoY but down 2.9% sequentially, with constant currency revenue dipping 3.3% quarter-on-quarter. For the full year ended March 31, revenue reached Rs130,144 crore, up 11.2% YoY, while net profit slipped 0.2% to Rs17,361 crore.
AI-led offerings continued to gain traction, with annualised AI revenue crossing $620 million in the March quarter and $155 million booked during the quarter itself, up 6.1% sequentially in constant currency terms. The CEO noted that AI is beginning to influence deal sizes, saying, “Something that was a $100 million deal could now be an $80 million deal because of the deflation,” while stressing that demand remained steady and pricing was being reshaped by AI-driven efficiencies embedded across client engagements. The company now segments its business into Traditional services, AI-enhanced offerings, and AI-native services.
Bookings and growth trends showed a mixed picture: total contract value (TCV) for the quarter was $1.94 billion, keeping full-year deal wins at $9.3 billion, broadly in line with the previous year. The overall growth narrative remained tempered by softness in discretionary spend and delayed decision-making, factors the management flagged as reasons for not meeting all internal expectations.
On the hiring front, the quarter added 802 employees, lifting headcount to 227,181. Fresher hiring remained robust with 11,744 graduates joining the year, while attrition stood at 12.5% on a trailing-12-month basis. The company reiterated FY27 guidance of overall revenue growth in the 1-4% range in constant currency terms, with services revenue expected to grow 1.5-4.5%, reflecting ongoing caution around discretionary spend but potential AI-driven upside if deal wins accelerate.
