No Runaway Profits: Insurance Rules Protect Policyholders
No Runaway Profits: Insurance Rules Protect Policyholders
Finance Minister outlines strict safeguards for India's insurance sector, boosting policyholder protections, solvency norms, and private participation.
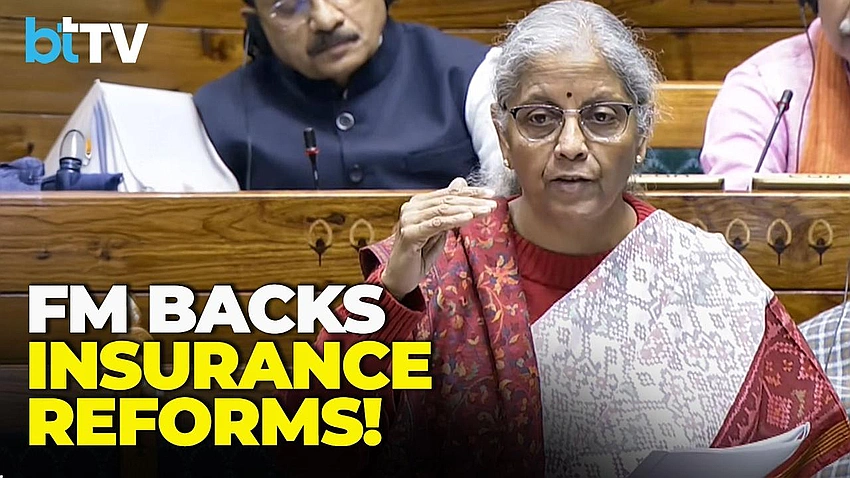
Finance Minister Nirmala Sitharaman outlined the government's ongoing safeguards shaping India's insurance landscape, stressing that policyholders remain fully protected. She highlighted a minimum solvency ratio of 1.5, ensuring insurers' assets are at least 1.5 times their liabilities, and said companies must set aside provisions for incurred-but-not-reported and under-reported claims before calculating profits.
On foreign investment and private participation, she noted that private insurers already play a big role in public schemes such as Jeevan Jyoti Bima Yojana and Suraksha Bima Yojana, enrolling over 20 crore beneficiaries. Capital infusions into public sector insurers have strengthened balance sheets, reduced losses, and improved performance, with two PSUs turning profitable.
During a broader defense of reforms since 2014, Sitharaman cited a total capital infusion of ₹17,450 crore into three public sector general insurers to bolster their balance sheets. She said that reforms have attracted flow of capital while expanding the number of insurers, and that India has seen growth in penetration, density, premiums and assets under management over the decade.
She also highlighted LIC's Bima Sakhi initiative, launched in December 2024, which has trained close to two lakh women as insurance agents to expand household coverage. She reminded that the government values its 14 lakh agents and will grant LIC greater operational autonomy to boost efficiency and outreach.
Taken together, the reforms aim to shield policyholders while inviting private investment and competition, signaling a more robust, inclusive insurance market for India.
