IRS Reveals 2026 Roth IRA and 401(k) Savings Limits Boost
IRS Reveals 2026 Roth IRA and 401(k) Savings Limits Boost
The IRS unveils higher 2026 limits for Roth IRAs, 401(k) contributions, and catch-ups, signaling a clearer path for savers next year.
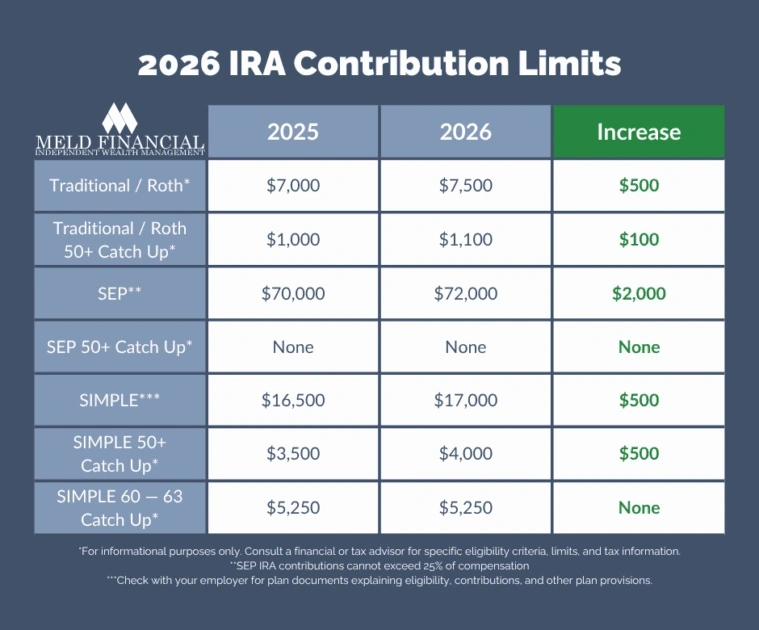
The Internal Revenue Service announced the 2026 limits for retirement accounts, signaling a significant shift for savers next year. The key highlights include higher Roth IRA income thresholds, an uptick in 401(k) contribution limits, and an increase in IRA contribution limits, alongside new catch-up rules for older savers.
Savers will see higher contribution caps across the board, allowing more of their income to go tax-advantaged into retirement accounts. The changes also affect who qualifies for Roth IRA eligibility, with income thresholds adjusted for 2026. Plan managers and financial advisors say the updates are designed to keep pace with inflation and long-term wage growth, potentially expanding access for higher earners while encouraging more consistent saving across age groups.
Financial experts urge account holders to review their 2026 limits early and adjust payroll deferrals or annual contributions accordingly. Since the numbers can influence year-end tax planning, it’s a good idea to check any employer plan rules and available catch-up opportunities for those aged 50 and older. The IRS notes that more details, including exact dollar amounts, will be released in the official guidance and on its website in the coming weeks.
